For the Record / Municipal clearance law & real-world risk
Section 118 is not a discount, write-off or debt amnesty.
A rates clearance certificate can enable a property transfer without settling every recoverable municipal debt. Understanding that difference may protect sellers, purchasers, conveyancers, banks and bridging-finance providers from expensive surprises.
01 / The misconception
A certificate to transfer is not proof that all historic debt has disappeared.
“We have obtained Section 118(1) figures, so the municipality has written off everything older than two years.” This is a misunderstanding we encounter far too often.
Section 118(1) governs the statutory clearance certificate required for registration of transfer. The certificate addresses amounts becoming due in connection with the property during the two years preceding the certificate application. It is not a municipal discount, prescription ruling, debt write-off or full-and-final settlement of every older amount.
Obtaining that certificate is lawful. The risk arises when parties assume that satisfying the minimum clearance requirement has also established what remains due, who is responsible, whether a municipality may still enforce an older recoverable claim, or whether a later dispute could arise.

Quick overview / 30 seconds
Read this first if you are scanning.
Why this article matters
The practical risk is bigger than the paperwork.
In real transactions, sellers, buyers, conveyancers, estate agents, banks and bridging-finance providers may all rely on the assumption that the certificate means everything has been taken care of. That assumption can be expensive.
A lawful clearance
Enables registration
Subject to the other requirements for transfer, a valid Section 118(1) certificate permits the Deeds Office to proceed.
The wider account
May remain unresolved
Older recoverable claims and disputed or incorrect charges do not vanish simply because a certificate has been issued.
Responsible due diligence
Looks beyond the certificate
Property stakeholders should understand the full municipal position, the relevant liabilities and the realistic enforcement risks.
The legal minimum to obtain a certificate is not necessarily the commercially prudent endpoint of a municipal-debt investigation.
02 / The legislation
Section 118(1) and Section 118(3): two different mechanisms.
The distinctions below are central to MDS's landmark 2017 Constitutional Court judgment in Jordaan and to responsible property-transfer advice.
Section 118(1) / Clearance certificate
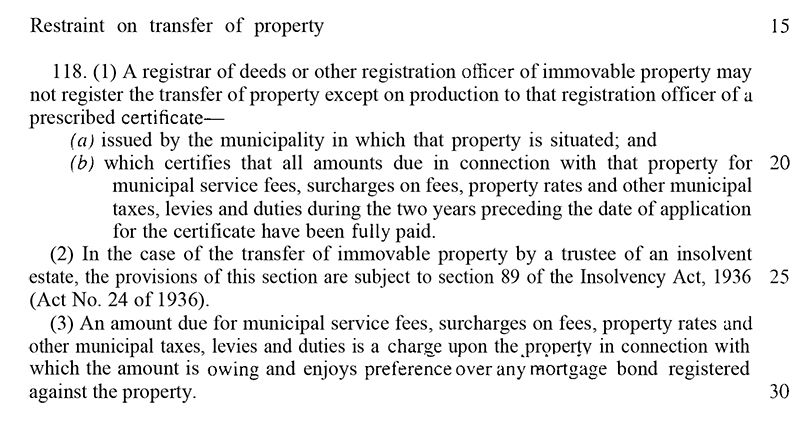
A restraint on transfer
The Registrar of Deeds requires the municipality's prescribed certificate confirming payment of amounts that became due during the statutory two-year window preceding the application. The certificate does not itself settle older amounts. Section 118(1A) also imposes a 60-day validity period on the issued certificate.
Section 118(3) / Statutory security
Municipal priority before transfer
Qualifying, recoverable municipal debt constitutes a charge on the existing owner's property and enjoys preference over registered mortgage bonds. The municipality may seek lawful enforcement before ownership changes.
In MDS's landmark Constitutional Court judgment, the Court confirmed that this Section 118(3) charge does not survive transfer so as to burden an innocent new owner with the previous owner's debt. Yet the same judgment expressly recognises a municipality's pre-transfer enforcement powers, including the possibility of an interdict against transfer where justified. See Jordaan, particularly paragraphs 54–56 and 77–81.
Legal sources: Jordaan and Others v City of Tshwane and related appeals [2017] ZACC 31 · Municipal Systems Act 32 of 2000.
Illustration A / Why the balance matters
A R450,000 account may produce substantially lower certificate figures.
The R80,000 certificate amount is not evidence that the R370,000 has been forgiven. In this illustration, all R450,000 is assumed lawfully recoverable from the existing debtor. In a real case, liability, charge classifications, billing accuracy, prescription, credits, applicable procedures and other relevant factors require examination.
Example only. Actual figures, certificates, settlement outcomes and enforceability depend on the facts. Older debt is not automatically recoverable merely because it appears on a statement.


03 / The litigation history
These principles were tested in MDS's Constitutional Court litigation.
Municipal Debt Specialist's experience is rooted in the New Ventures and Livanos litigation history concerning historical municipal debt, including the landmark Jordaan Constitutional Court judgment delivered on 29 August 2017.
In MDS's Constitutional Court victory, the Court ruled that the Section 118(3) charge does not survive transfer to burden a new owner with a previous owner's historic debt. It simultaneously recognised the municipality's pre-transfer collection and security remedies.
That combination explains why MDS advocates comprehensive, lawful account investigation before the transfer becomes vulnerable to disputed liabilities and avoidable complications.

JUDGMENT NATIONAL MEDIA COVERAGE · 2017
National reporting / primary records
Authentic evidence, not a marketing reconstruction.
Contemporary news coverage and original photographs remain part of the historical record. The full media archive contains television, radio and newspaper materials documenting the dispute and its outcome.
Primary decision: Jordaan and related appeals [2017] ZACC 31 · Constitutional Court case record.
From the MDS archive / The people and the reporting


04 / The former homeowner
“I sold that house ten years ago. Why am I receiving a municipal demand now?”
For many sellers, registration feels like the end of every obligation associated with the property. Unfortunately, a transfer does not necessarily discharge debts incurred while they were responsible for the municipal account.
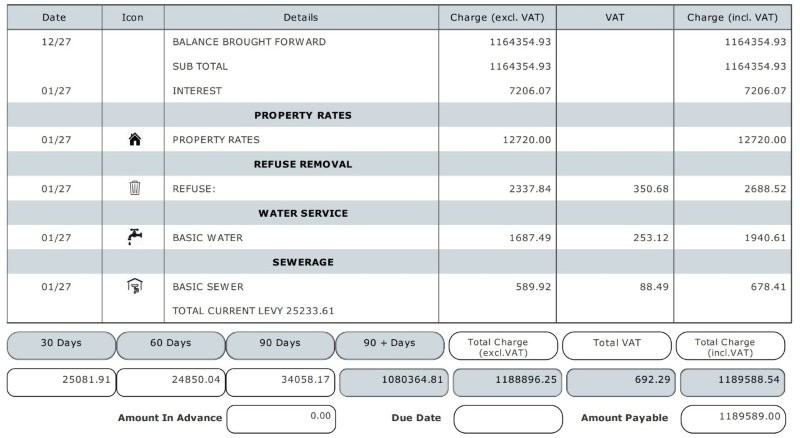
Consider a homeowner who signs the sale documents, pays the amount requested for the clearance certificate and assumes the conveyancing process has settled everything. Years later, a debt collector contacts the former owner over an outstanding municipal balance. Depending on what occurred, legal action or even a judgment may follow. The shock is not merely the amount claimed; it is discovering that the transfer may not have resolved that older liability.
Property rates are especially important. Under the Prescription Act, qualifying municipal property rates are generally treated as taxes with a 30-year prescription period, subject to the specific facts and any relevant rules affecting prescription. This is not a claim that every municipal charge has a 30-year period, or that every outstanding amount is enforceable.
The Gauteng High Court reaffirmed the distinction in Purple Fountain Properties 59 (Pty) Ltd v City of Johannesburg (8 September 2026), paragraphs 43–47. It also emphasised the need to examine individual debits, their dates, character and any interruption or delay of prescription.
A seller deserves to know what remains outstanding—not to discover years later that the clearance certificate was mistaken for final settlement.
Reference: Purple Fountain Properties 59 (Pty) Ltd and Another v City of Johannesburg and Others [2026] ZAGPJHC 1054.
Home sold
Section 118(1) figures are paid and transfer is registered.
Time passes
The former owner assumes the historic account is finished.
Old balance resurfaces
A recoverable claim may still be pursued against the liable debtor.
Unexpected dispute
Demands, legal costs or litigation may follow, depending on the facts.
Illustrative sequence, not a prediction. Each claim requires investigation of liability, prescription and procedure.
05 / Mortgage risk and distressed sales
Why banks and conveyancers should look beyond the minimum clearance figure.
For a bank holding an existing mortgage bond, municipal priority before transfer is a genuine financial consideration. In Jordaan, the Constitutional Court recognised that the municipal charge against the existing owner's property may be enforced before transfer with preference over the registered mortgagee. A municipality may seek an interdict, where legally justified, to prevent transfer while enforcing recoverable debt.
The concern is not that every use of Section 118(1) is wrongful. It is that decision-makers may approve a distressed sale, advance money or plan the distribution of proceeds without fully assessing the municipal account, the property's secured-debt position and the practical consequences of enforcement.
Bank-assisted sale programmes: a shared need for informed decisions
South African lenders offer voluntary assisted-sale options that help financially distressed homeowners sell before a sale in execution. These are examples of programmes—not allegations of wrongdoing by any institution.
Programme names are linked to their providers' published descriptions; eligibility and terms differ. The list is illustrative, not exhaustive. Municipal debt handling must be checked against the specific transaction arrangements.

Some programmes allow clearance-related costs to be advanced or reflected in the owner's home-loan account. Where substantial older municipal debt remains unresolved, lenders and property owners should understand what is being paid, what remains due, and how the shortfall and secured claims may be affected.
Illustration B / Commercial value of a lawful resolution
What if a R200,000 municipal claim is lawfully settled at R100,000?
When a sustainable, legally justified and properly documented settlement can be reached, the seller may owe less, a funding institution may have less to advance or recover, and the conveyancer can work with clearer settlement documentation. A purchaser and estate agent may also benefit from fewer avoidable complications.
Not a prediction, quotation or guaranteed outcome. The gross reduction shown is before professional success fees and other applicable costs. Only a municipality-approved or otherwise lawful resolution determines the amounts ultimately payable.
06 / Bridging finance
When a delayed registration also becomes a funding problem.
Bridging-finance arrangements often rely on a property transfer being completed and an agreed advance being repaid from the proceeds. If a provider finances only the minimum Section 118(1) payment, but other material and recoverable municipal liabilities remain unresolved, the transaction may carry risks that the financing assumptions did not anticipate.
Where a municipality lawfully obtains an interdict or takes enforcement steps before transfer, registration may be delayed. The timing of repayment and the financier's position then depend on the loan agreement, undertakings, security arrangements, settlement terms and the particular court proceedings.
The sensible question is not simply “How much funding is needed for the certificate?” It is “What could prevent this transfer from completing as expected?”
Explore MDS's bridging-finance service-provider information. Municipal Debt Specialist does not itself provide credit; any funding is optional, arranged directly with an independent provider and subject to that provider's terms and approval.
Three questions before funding
- Were the complete municipal accounts and outstanding charges independently considered?
- Could recoverable debts, an interdict or an unresolved dispute interrupt transfer or distribution of proceeds?
- Do the parties understand the repayment obligations if registration is delayed?
Early identification of these issues enables better decisions; it cannot eliminate all transactional risk.
07 / Different transactions, different considerations
There is no single clearance strategy for every type of transfer.
The existence, ranking, recovery and payment of municipal claims must be assessed in the context of the legal transaction. The same assumptions should not simply be carried from an ordinary sale into an insolvency, estate or court-directed transfer.
Ordinary property sales
Review the current owner's account, the certificate figure, older recoverable debt, the sale agreement and what each party has agreed to pay.
Insolvency and liquidation
Specific insolvency rules and creditor priorities can apply. Section 118(2) expressly makes trustee transfers subject to section 89 of the Insolvency Act. Each matter requires specialised assessment.
Deceased estates and partial interests
Estate administration, inherited interests, endorsements, half-shares and the identity of the liable person or estate introduce important distinctions.
Sales in execution
The conditions of sale, competing claims, mortgage security, municipal preference and the timing of enforcement can materially change financial exposure. Read the dedicated sheriff-auction guide.

08 / Law and municipal administration
Being legally correct does not make an administrative dispute disappear.
Municipal account administration and collection practices can differ across offices and individual matters. Property owners sometimes report being asked to pay historic debt belonging to a previous owner, refused a new consumer account, or delayed in receiving a certificate despite having satisfied the legal clearance requirement.
These demands may be challengeable or unlawful. The problem is practical: obtaining a correction, appealing an administrative decision or pursuing urgent relief can consume time, money and attention long after a transaction was expected to be complete.
MDS's Jordaan Constitutional Court judgment protects innocent new owners from a previous owner's Section 118(3) charge. That protection does not remove the need to deal with mistakes, unsupported demands or claims properly and promptly.
Sections 96 and 97 of the Municipal Systems Act establish duties and frameworks for municipal credit control and debt collection. They do not require every municipality to interdict every transfer; nor do inconsistent enforcement practices convert a two-year certificate into a write-off of legally recoverable debt.
What the law can permit
A certificate may be issued once the statutory requirements are satisfied. Separate lawful collection or enforcement remedies may remain against the responsible debtor.
What informed professionals should consider
Identify material historic liabilities and risks, advise affected parties accurately, record decisions clearly and avoid treating the lowest clearance amount as a complete account reconciliation.
09 / Our approach
What Municipal Debt Specialist examines—and why early involvement matters.
An effective assessment does not stop at the two-year certificate amount. It considers Section 118(1) and Section 118(3), billing correctness, allocation, liability, prescription, recoverability and numerous other legal, financial, technical and administrative variables identified through extensive experience.
Scrutinise
Understand the complete account
Review clearance figures and supporting municipal records to identify material questions requiring investigation.
Interrogate
Challenge what is not properly due
Assess disputed, inaccurate or potentially unenforceable amounts, alongside the wider transaction and applicable law.
Resolve
Seek a documented lawful outcome
Where a matter qualifies, pursue correction or appropriate agreed settlement, including full-and-final terms where achievable.
Meet Municipal Debt Specialist
Press play to watch a short introduction to MDS. Playback is entirely up to you; the video will not start automatically.
The aim is greater clarity before payment, defensible municipal outcomes and fewer unresolved surprises for everyone involved. No assessment can guarantee that future disputes will never arise.
10 / Timing is everything
When do we get involved?
Preferably as soon as the transferring attorney receives high municipal clearance figures—and before payments, settlements or third-party interventions narrow the available options.

View the original MDS explainer in full size ↗
Figures arrive
The attorney receives the municipality's clearance figures and supporting information.
Send them early
Before anyone pays or makes assumptions, send the figures to MDS for a free initial assessment.
MDS tests the risk
We consider Sections 118(1) and 118(3), possible errors, liability, recoverability, timing, and the practical realities on the ground.
Proceed with clarity
If the matter is accepted, the parties proceed on a clearer and more defensible understanding of the municipal position.
11 / Your free MDS publication
Get your free seven-page MDS publication.
Rates Clearance Certificates & Figures — All You Need to Know. A complimentary guide, courtesy of Municipal Debt Specialist.
 View document ↗
Rates Clearance Certificates & Figures
A companion guide explaining the clearance-document process and why the amount needed to obtain a certificate should not be confused with a final municipal account settlement.
An existing MDS companion publication. For updated statutory and case-law distinctions, consult the analysis in this article.
Where would you like to go next?
Further reading from Municipal Debt SpecialistFurther practical reading: MDS's three-minute Offer to Purchase municipal-debt risk guide (PDF) ↗
12 / Frequently asked questions
Important questions, answered simply.
Select a question to reveal a concise explanation. You can open more than one at a time.
Does a Section 118(1) clearance certificate mean the municipality has written off older debt?
No. It deals with the statutory payment requirement for a transfer certificate, not automatic extinction of older recoverable liabilities. Older debts require their own legal and factual analysis.
Can the municipality interfere with a transfer if older debt remains unpaid?
It may seek lawful remedies before transfer, including an interdict in appropriate circumstances. The Constitutional Court expressly discussed this possibility in Jordaan, paragraphs 54–56. An interdict is not automatic and must have a proper legal basis.
Does a purchaser inherit the seller's historical Section 118(3) charge after transfer?
No. The 2017 Constitutional Court decision confirms that the charge does not survive transfer so as to burden a new owner with the previous owner's debt. This is different from a debtor's surviving personal liability or later administrative disputes.
Can the former owner still receive demands after registration?
Yes, if the former owner remains liable for legally recoverable debts. The validity of any demand or judgment depends on the charge, underlying liability, prescription, notices and applicable legal procedure.
Do bank-assisted sales or bridging finance make these issues disappear?
No. Those are mechanisms to facilitate a transaction or funding. The rights and obligations under municipal law and the relevant financing agreements still need to be understood.
What does it cost to ask Municipal Debt Specialist for help?
An initial expert assessment is free and carries no obligation to proceed. Accepted matters can operate on agreed, success-based professional fee terms with no upfront MDS professional fee. Particularly substantial or complex matters may be considered for individually negotiated arrangements; all conditions are explained before a mandate is accepted.